

Nagad Uddokta
by Nagad Limited
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
If you are a Nagad Uddokta handling customer transactions, Nagad Uddokta is designed to be a work-focused finance app rather than a general wallet for casual personal use. I approached it with that distinction in mind, because the first important question is not whether it looks impressive, but whether it fits the daily routine of someone serving customers through the Nagad channel.
The app comes from Nagad Limited and is free to install. It sits in the finance category, carries an Everyone age rating, and supports devices running Android 5.0 or later. Its current version is 1.0.119.01, while its public release date was April 28, 2020. Those details make it accessible to people using older Android phones, which matters for a work tool that may need to run on a device chosen for reliability rather than premium hardware.
In my experience, the most useful way to judge this app is to imagine a real working day: a customer arrives, asks for a transaction, and expects the process to be handled accurately without unnecessary delay. The app’s value comes from supporting that channel-based workflow. It is not something I would install simply to explore mobile finance services as a personal user.
What to expect before using it
The store summary describes the app as a channel app for Nagad Uddokta, and that short description is important. It tells you that the intended audience is an Uddokta, not every Nagad customer. If you are looking for a personal money-management app, a standard consumer wallet would be a more natural starting point. Installing this one without that role in mind could leave you wondering why its purpose feels narrower than other finance apps.
For the right user, that narrower purpose is a strength. A dedicated channel app can keep work activities separate from personal spending, which is useful when a phone is used at a shop or service point. I prefer that separation because it reduces the chance of confusing customer-related activity with my own wallet activity. It also gives the app a clear job: support the Uddokta side of Nagad usage.
The app has built a sizeable audience, with more than five million installs and an average rating of 4.2 from roughly thirty-five thousand ratings. I would treat that as a useful sign of broad adoption, not as a guarantee that every user will have the same experience. A finance app can feel convenient when the account is ready and the user understands the workflow, yet feel difficult when the setup or account status is not aligned with the intended role.
Before installing, I would make sure I am actually using the app for Nagad Uddokta work. That single check prevents the most common mismatch. If my goal is to send money for myself, check a personal balance, or manage ordinary household payments, I would choose the consumer-facing option associated with that task instead.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Preparing for the first launch
My advice for a first-time user is to treat the first launch as an account and role check, not as a moment to rush into a customer transaction. Have the mobile number and account details connected with the Uddokta service available, and use the same device and contact information you normally rely on for that work. I would also avoid beginning during a busy customer queue, because the first session is the wrong time to discover an account or sign-in issue.
The app is free, but “free” should not be confused with “ready without preparation.” The application itself does not replace the need for an appropriate Nagad Uddokta account or working credentials. If you are a new agent, the practical first step is to understand how your Uddokta access is issued and supported before expecting the app to behave like an open registration service.
On an older Android phone, I would first make sure there is enough space for a normal installation and that the device is running a supported system. The minimum requirement is Android 5.0, so the app is not limited to recent phones. Still, an older device may respond less quickly when several apps are open. Closing unrelated apps before a busy work session is a simple habit that can make the experience feel steadier.
I would also keep the phone dedicated to the person responsible for the account during transactions. That is not a special feature claim; it is sensible handling for any financial tool. A shared phone makes it harder to know who initiated an action, and it can create avoidable confusion when another person changes settings, signs out, or uses a different account.
Getting through setup without guessing
When I first open a finance app intended for channel work, I look for the difference between registration, sign-in, and transaction access. These are not always the same thing. A screen asking for a number does not necessarily mean I can create a new Uddokta account there, and a successful login does not automatically mean every work action is available. Reading each prompt carefully is safer than repeatedly trying different details.
If a verification step appears, I would use the phone number and information associated with the Uddokta account rather than a personal number chosen for convenience. I would never share a verification code with a customer or another person standing nearby. A customer may need help understanding a transaction, but the authentication step belongs to the account holder.
One practical tip is to keep a written, private record of the correct work identity and the order in which you normally handle customer requests. I do not mean writing down passwords or sensitive codes. I mean keeping the routine clear enough that I do not improvise under pressure. In a channel environment, accuracy is often more valuable than saving a few seconds.
If setup does not proceed, I would not repeatedly uninstall and reinstall the app as a first response. That can remove local app data without solving an account-side issue. Instead, I would check the phone number, connection, app version, and account status in that order. If the problem remains, the appropriate support route for the Nagad Uddokta relationship is more useful than random trial and error.
Reaching the first meaningful success
The first meaningful success is not simply seeing the home screen. It is completing a legitimate Uddokta task correctly while understanding what the app is asking at each stage. I would begin with a quiet practice moment, not the middle of a line of customers. That gives me time to confirm the customer details, review the amount, and notice whether the app presents a final confirmation before anything is submitted.
My preferred routine is deliberately repetitive. I identify the customer’s requested service, enter the required information slowly, pause to compare the displayed details with what the customer gave me, and only then continue. After the action finishes, I keep the confirmation information available according to the normal business process. This approach may feel slower on the first attempt, but it prevents the far more expensive mistake of correcting an incorrect transaction.
A useful non-obvious habit is to separate “data entry time” from “confirmation time.” I do not ask the customer to speak while I am still typing, because that makes it easier to miss a digit or mishear a number. Once the details are entered, I show or read back the relevant information in a privacy-conscious way and ask for confirmation before proceeding. The app can support the workflow, but it cannot replace careful communication between the Uddokta and customer.
Another helpful habit is to avoid treating a loading screen as proof that an action failed. A slow response may tempt me to press the same control again, which can create uncertainty about whether the first request was accepted. I would wait for a clear result and check the transaction state through the available confirmation information before attempting anything again. In financial work, duplicate actions are a bigger concern than a short pause.
For a small shop, this routine is especially valuable during busy periods. Imagine a customer arriving just before closing and asking for help with a Nagad service. I would rather spend an extra moment checking the entered number and final result than rush because another customer is waiting. The app can make the process more organized, but the Uddokta’s verification discipline remains the main safeguard.
Where first-time users may feel confused
The biggest source of confusion is likely the app’s role. Someone familiar with a personal wallet may expect a broad dashboard of personal finance tools, while this application is built around the Uddokta channel. If the opening experience feels specialized, that is not necessarily a defect; it reflects the intended user. The correct question is whether the available path matches the work I am authorized to perform.
Another point of confusion is the difference between an app problem and an account problem. If I cannot complete setup, that does not automatically mean the installation is broken. A wrong number, an account that is not enabled for the expected role, or a temporary connection issue can all look similar from the user’s point of view. I would record the exact message shown and the step where it appeared before seeking help.
I would also avoid assuming that an old successful login proves the account is permanently ready. Finance services can depend on current account status and correct authentication. If the app worked previously but now behaves differently, I would check whether I am using the intended account and current version before changing the phone or attempting repeated transactions.
Privacy creates another practical challenge. A customer may need to verify information, but displaying an entire account screen in a crowded shop can expose details unrelated to that transaction. I would show only what is necessary, keep notifications private when possible, and lock the phone whenever I step away. These habits are particularly important because the device may contain both business information and personal data.
There is also a human limitation: the app is not a substitute for training. A first-time Uddokta should learn the correct service procedure and customer verification expectations separately from learning which buttons to press. The application can guide a transaction, but it cannot decide whether a request is legitimate, whether the customer has supplied the right information, or whether I should stop and ask for assistance.
How it compares with ordinary finance alternatives
Compared with a personal mobile wallet, Nagad Uddokta is more appropriate when I am operating on behalf of a Nagad channel and serving other people. A consumer wallet is usually the better fit for personal transfers, household payments, and managing my own money. Trying to force either app into the other role creates unnecessary complexity and can blur responsibility.
Compared with handling work through informal notes, messages, or a general banking application, a dedicated Uddokta tool has a clearer operational purpose. I would not want customer activity scattered across unrelated apps, especially when I need to review what happened during a busy day. The trade-off is that a specialized app may feel less flexible for users who want one application to cover every financial need.
Compared with a desktop workflow, a phone-based channel app is more practical for a small counter or mobile service setting. I can work from the device already used at the point of service rather than depending on a larger computer. The trade-off is screen size: reviewing numbers and confirmation details requires more concentration on a phone, particularly for users with older or smaller displays.
That comparison leads to a clear recommendation. I would choose this app when my daily work is specifically tied to Nagad Uddokta activity and I want that work on an Android phone. I would skip it if I am only a personal Nagad customer, if I need a broad budgeting tool, or if my organization requires a different platform for records and supervision.
Building a safer daily routine
Once the first successful action is complete, the next step is not to explore every screen at random. I would build a repeatable opening routine: confirm the correct account, check that the app is responsive, keep the phone available to the authorized user, and prepare a quiet way to verify customer details. This takes little time and reduces the chance of beginning a transaction while distracted.
I would keep the app updated when a trusted update is available, especially because the current version is 1.0.119.01. Updating is not a promise that every issue disappears, but it helps ensure I am not working from an outdated installation. After an update, I would perform a low-pressure check before serving a long queue, since an interface change can affect where I expect to find a confirmation or account control.
A second advanced habit is to reconcile the day’s activity using the records available through the normal Uddokta process, rather than relying on memory or a customer’s message alone. I would compare my own shop notes with the app’s completed transaction information and investigate any mismatch promptly. This is especially useful when several customers request similar amounts or services close together.
I would also establish a clear rule for interruptions. If a customer walks away, the network becomes uncertain, or someone asks me to switch tasks halfway through, I would stop and identify the current transaction state before continuing. I would not begin a second action simply because the first screen looks slow. This small discipline is one of the most important trade-offs in mobile finance: speed matters, but certainty matters more.
The app’s broad adoption suggests that it is a practical choice for many Uddokta users, and the 4.2 average indicates generally positive reception. My own judgement is more specific: its usefulness depends heavily on whether the account role, phone, and work routine line up. A good rating cannot make the wrong user profile fit, and a specialized design should not be criticized for failing to behave like a personal wallet.
For someone deciding today, I would describe it as a focused tool with a sensible place in a Nagad service routine. It is free, supports older Android versions, and is aimed at the person handling channel transactions rather than the person casually managing personal funds. The main limitations are the narrow audience, the need for correct account access, and the care required when entering and confirming customer information.
My final advice is simple: install it only for the Uddokta role, prepare the correct account details before opening it, and make your first real action when you are not under pressure. Once the setup is understood, use a pause-and-confirm routine for every customer and keep transaction records organized. For the right Nagad channel user, the app is most valuable not because it removes responsibility, but because it gives that responsibility a dedicated mobile workspace.
Pros
- Lets agents serve customers in areas with limited banking access.
- Supports everyday transactions from a single agent account.
- Can help local businesses attract more walk-in customers.
- Useful for users who prefer nearby cash-based financial services.
- May reduce travel time for routine mobile-money transactions.
Cons
- Requires reliable internet and a compatible Android device.
- Agent earnings may depend heavily on transaction volume and location.
- Cash shortages can limit withdrawals or cash-in services.
- Users may face delays during maintenance or service interruptions.
- Agents must carefully protect PINs, phones, and customer information.
FAQs for Nagad Uddokta
What is Nagad Uddokta used for?
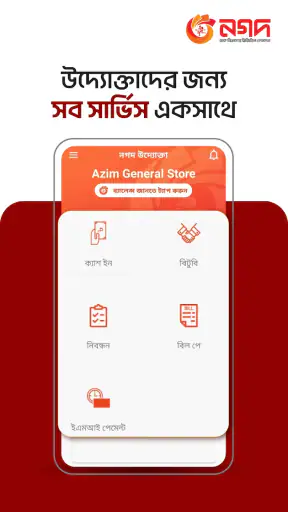
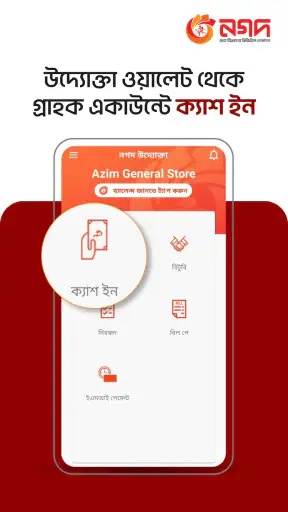
Nagad Uddokta is a mobile financial service application designed for authorized Nagad agents in Bangladesh. It helps registered entrepreneurs provide services such as cash-in, cash-out, mobile recharge, balance transfers, bill payments, and other supported transactions for customers. The app is primarily intended for business use, not for ordinary users who simply want to manage a personal Nagad wallet.
Who can register for a Nagad Uddokta account?
Registration is generally intended for approved Nagad Uddokta or agent businesses operating in Bangladesh. Applicants may need to provide valid identification, business information, a mobile number, and other documents requested during verification. Approval is not necessarily automatic, and eligibility can depend on Nagad’s current policies, location, business type, and compliance requirements.
Is Nagad Uddokta safe for handling financial transactions?
Nagad Uddokta includes account authentication and transaction security measures, but users should still treat the application as a financial tool requiring careful handling. Never share PINs, one-time passwords, or verification codes with customers or other people. Before confirming a transaction, check the recipient, amount, and service details, and use only the official app downloaded from a trusted source.
Does Nagad Uddokta charge fees for transactions?
Transaction charges, commissions, and service fees may vary according to the type of service, customer category, transaction amount, and Nagad’s latest commercial policies. Some services may provide an agent commission, while others can involve a customer charge or operational fee. Review the fee information shown in the app and confirm current terms with official Nagad support before relying on a specific rate.
What should I do if a transaction fails or money is missing?
If a transaction fails, remains pending, or appears to have an incorrect amount, first check the app’s transaction history and save the transaction ID, date, time, phone number, and screenshots. Avoid repeating the transaction until its status is clear, because duplicate attempts can create additional problems. Contact official Nagad agent support promptly and never trust unofficial callers promising instant refunds.











